JPMorgan Chase Drops the Hammer
Happy Monday, Fintech Takers!
Today’s newsletter comes to you from Washington, D.C.
It’s apparently crypto week here (which I did not know when I booked my trip), but it’s also financial inclusion week (which is why I’m here) and, due to some breaking news that I will cover in today’s newsletter, open banking week (which I am glad to be here in person for).
We have much to discuss today, so let’s get right into it!
- Alex
P.S. — There’s still time to register for Wednesday’s Fintech Office Hours, which is open to everyone this month!
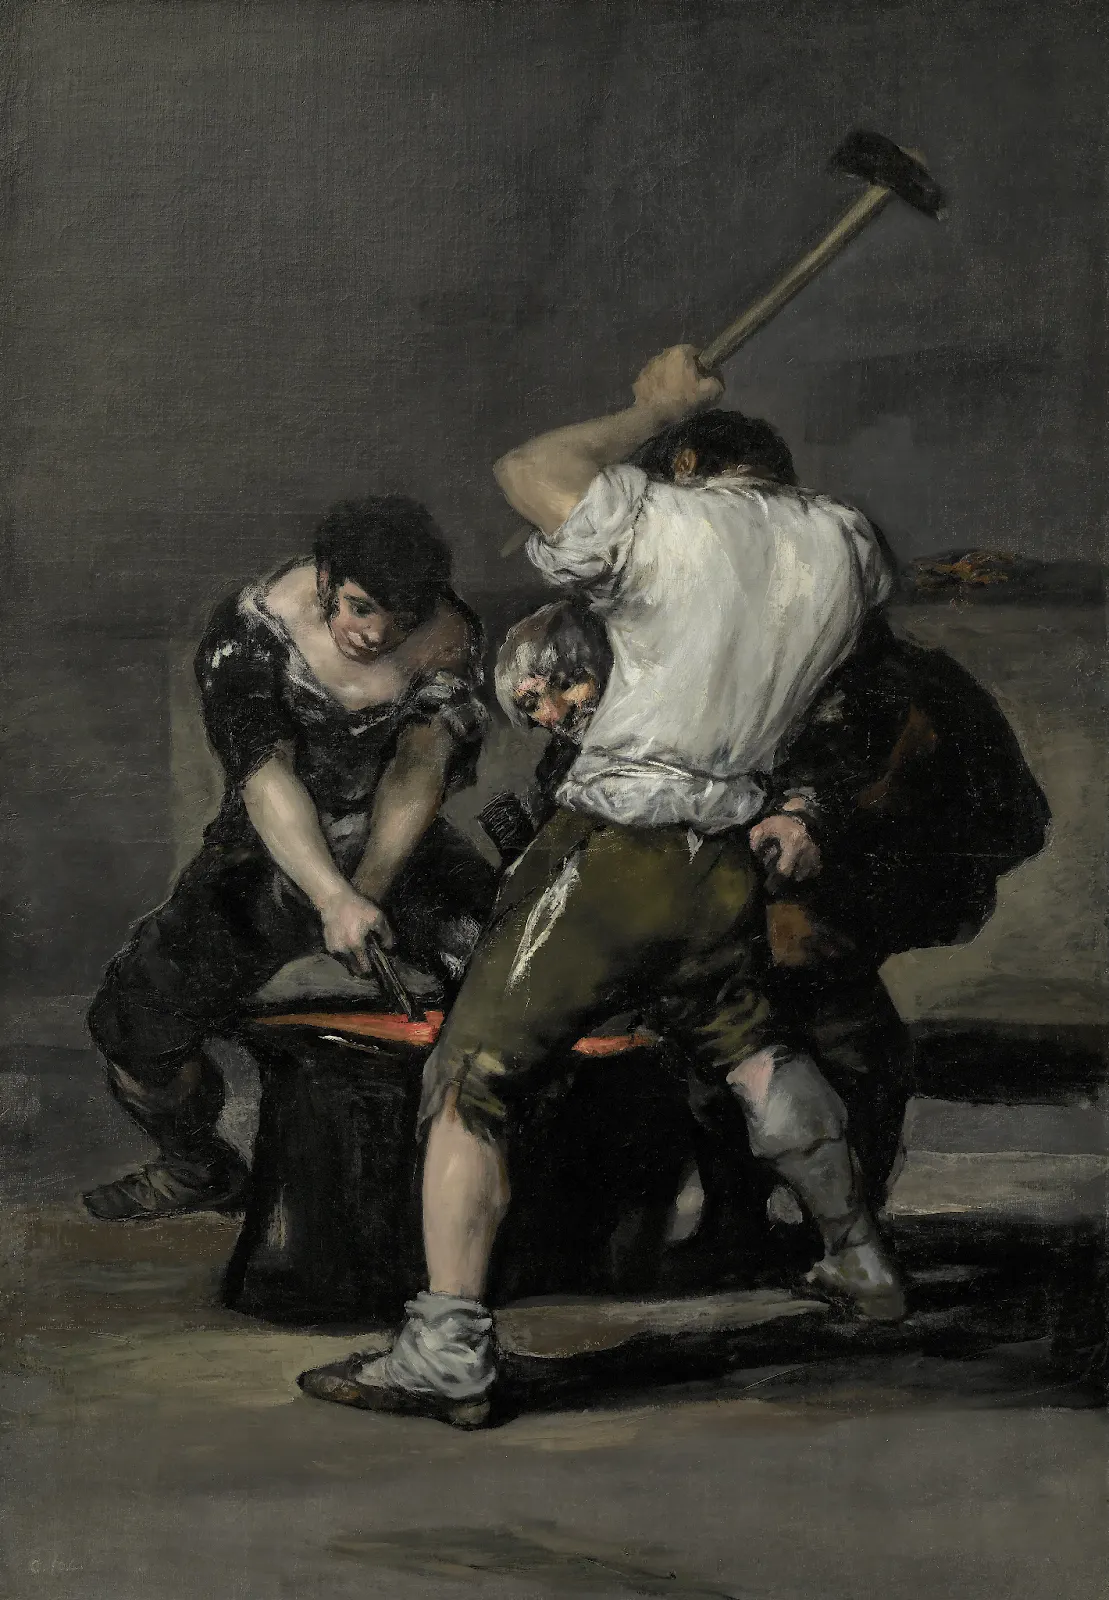
The Forge (1815-1820) by Francisco Goya.
3 FINTECH NEWS STORIES
#1: JPMorgan Chase Drops the HammerCopy anchor linkCopied
What happened?Copy anchor linkCopied
JPMorgan Chase put the hammer down on open banking. Evan Weinberger and Paige Smith at Bloomberg report:
JPMorgan Chase & Co. has told financial-technology companies that it will start charging fees amounting to hundreds of millions of dollars for access to their customers’ bank account information – a move that threatens to upend the industry’s business models.
The largest US bank has sent pricing sheets to data aggregators — which connect banks and fintechs — outlining the new charges, according to people familiar with the matter.
So what?Copy anchor linkCopied
I’ll tell you what.
Just for a moment, let’s set all of the consumer-focused morality arguments for and against open banking aside. Just for the sake of clarity, let’s not allow ourselves to fall back on bulletproof rhetorical statements like, “It’s the customers’ data and they can do what they want with it,” or “All we are trying to do is keep our customers’ data safe.”
There is some truth in those statements, but they also tend to muddy the water during arguments about the virtues and drawbacks of consumer-permissioned data sharing in financial services.
Instead, let’s talk about this news purely in economic and antitrust regulatory terms.
Fundamentally, we have three parties: banks, fintech companies, and data aggregators.
Banks are the incumbents. They have the most market share. They are chartered and supervised directly by the government, and that regulatory status guarantees banks, as a group, participation in a set of economically important financial activities, including the storage, movement, and lending of money.
Fintech companies are the disruptors. They are trying to take market share away from the banks. They are subject to significantly less government regulation than banks. However, that reduction in direct regulation also means that most of those same economically important financial activities can’t be done entirely by fintech companies. They require bank partners.
And finally, we have data aggregators. These are intermediaries that sell access to consumers’ data to fintech companies and banks. That data can be used to help facilitate these economically important financial activities. Historically, data aggregators have been (mostly) unregulated by the government.
Now, here’s the question: If I ask you to step into the original position behind the veil of ignorance, and design a set of rules to govern this ecosystem, in a way that maximizes overall utility for financial services consumers, what rules would you come up with?
I genuinely would be curious to hear your answers to this question, but, in the meantime, here are two guiding principles that occur to me:
- Consumers benefit from competition, and in the digital-first world that we live in today, data portability is essential to competition.
- Participation in economically important financial activities should be closely regulated to ensure safety and soundness and consumer protection. And the resulting costs should fall proportionally on the various participants.
I know that JPMorgan Chase agrees with that second principle. It said as much in a statement to American Banker:
We've invested significant resources creating a valuable and secure system that protects customer data … We've had productive conversations and are working with the entire ecosystem to ensure we're all making the necessary investments in the infrastructure that keeps our customers safe.
However, as the largest bank in the U.S., we can also safely assume that JPMC disagrees with the first principle, even if it’s careful to never say so out loud.
In this specific case, two pieces of evidence suggest that JPMC’s motivation for this move is more about squashing competition than it is about supporting their customers and protecting their data.
First, the proposed pricing is ludicrously high. Here’s Bloomberg again:
JPMorgan’s proposed fees in some cases would eclipse the revenue certain companies generate on a single transaction by as much as 1000%, one of the people familiar said.
My own reporting on this news is consistent with what Evan and Paige were told. The proposed pricing (which JPMC and the data aggregators are currently negotiating over) is based on volume tiers. The highest-volume aggregators would end up paying the bank approximately 10x what they make in revenue from JPMC customer data. For lower-volume aggregators (or fintech companies that go direct to the bank), the price would be even higher.
Second, the proposed pricing differentiates by use case:
The fees vary depending on how companies use the information, with higher levies tied to payments-focused companies, the people said, asking not to be identified discussing private information.
Again, this matches up with what I’ve been told by sources. API calls for payments use cases (in which JPMC is returning a tokenized account number or TAN) are roughly 10x as expensive as API calls for non-payments use cases.
These facts simply do not fit the case, which industry observers like Tom Noyes have been making, that JPMC is just looking to support and protect its customers and get reasonable compensation for the costs it incurs to do so.
The impact of payments use cases on banks’ digital infrastructure is actually less severe than it is for many non-payments use cases, such as earned wage access (EWA), which require consistent monitoring of customers’ accounts, rather than the one-time pull of a TAN.
You could argue that the all-in costs (which include the infrastructure as well as compliance and customer support) for payments use cases are higher (this may be true), but it’s hard to take JPMC’s word on that given its obvious incentive to set prohibitively high fees for use cases that threaten its core business.
On a broader level, this news really bums me out.
I am actually very sympathetic to the argument that the CFPB’s Personal Financial Data Rights Rule didn’t adequately address banks’ concerns about liability, third-party risk management, and cost-sharing.
My hope, late last year, was that the second Trump Administration would take an APA scalpel to the rule, to solve for these very reasonable concerns without weakening its larger pro-competition effects, which the first Trump Administration so clearly valued when it initiated the formal rulemaking process back in 2020.
Instead, Russ Vought and Mark Calabria hit the rule with a sledgehammer, and now JPMorgan Chase is seizing its opportunity to remake the fintech ecosystem into an image more to its liking.
I’m sure lots more news on this front will be coming soon. Here are a few open questions:
- Will the Personal Financial Data Rights Rule end up being vacated by the court? I truly have no idea. JPMC isn’t stupid, and this is a pretty aggressive move, so I’m guessing that it feels confident. Plus, the court just refused to accept amicus briefs from two trade associations and three nonprofits in support of the rule, which is both strange and troubling.
- Will other big banks follow JPMC’s lead? I’m guessing yes. From what I hear, PNC and Bank of America are both considering it, although JPMC is the only one that has the flexibility in its data access agreements with aggregators to move this fast. The others will take more time.
- What about Akoya? Great question! The folks I talk to tell me that Akoya has also been given the same pricing sheet from JPMC. Not shocking, given that it would have triggered massive antitrust red flags if the bank had given an exemption or preferred pricing to a vendor it is a part owner in. Still, this move screws over Akoya as much as it does the other aggregators, and, as a consequence, it also screws over the other banks that have invested in Akoya.
- Will we see a surge in screen scraping? If the rule gets vacated and the pricing stays anywhere close to where it is now, I can guarantee that screen scraping will roar back with a vengeance. It’ll be the only leverage that aggregators and fintech companies have, and they will use it (with an assist from AI).
- What about stablecoins? On and off-ramps for stablecoins are a popular (and growing) payments use case for open banking, and this will throw a wrench in the works. I predict that we will see a lobbying alliance form between the open banking and crypto industries, both of which despise JPMC.
#2: Bellerophon Jumps OffCopy anchor linkCopied
What happened?Copy anchor linkCopied
Bilt officially announced a new round of funding and some interesting product roadmap updates:
We're thrilled to announce that Bilt has raised $250 million in new primary funding, valuing our company at $10.75 billion. The round was led by General Catalyst and GID with further investment from United Wholesale Mortgage.
We're announcing our expansion into mortgage through direct partnerships with mortgage servicers, revolutionizing the mortgage experience from origination through servicing on to loyalty.
Earlier this year, we received incredible feedback from tens of thousands of our Members about what they wanted from their Bilt Card experience going forward. Based on that feedback, we have been developing new cards that deliver the depth and breadth of product experience you all have asked for. Bilt Card 2.0 is being developed in partnership with Cardless—the platform which recently launched the American Express Coinbase card. The new card lineup will include three distinct products designed to serve Bilt's diverse member base: a no-fee card option, along with premium cards featuring $95 and $495 annual fees, respectively.
So what?Copy anchor linkCopied
When it was first reported that Bilt was raising this round, I wrote:
We use the term “unicorn” in tech to describe a rare breed of private company, one that has achieved a valuation of $1 billion or more. We can argue whether that term is still fit for purpose, given the growth of the venture capital ecosystem over the last decade. However, the broader point is that while unicorns are rare, there are more than one of them out there.
Bilt isn’t a unicorn. It’s more like Pegasus, sired by the Gods and the possible bane of any who dare to ride him.
What I meant by this is that Bilt’s ability to create partnerships with other companies (aided by the CEO’s family connections) to bring its ‘neighborhood loyalty network’ to life is completely unique and unreplicable.
I continue to strongly believe this.
The company convinced United Wholesale Mortgage to kick in $100 million into this funding round, which is a strategy that it has utilized to great effect with other partners (e.g., Wells Fargo) and customers (e.g., many of the big property management companies).
That investment will, apparently, be a springboard for Bilt to expand into mortgages and homeownership. It’s not clear to me exactly what Bilt will do in this space or how it will manage the inherent conflicts between property management companies (which want to keep people renting for as long as possible) and mortgage brokers and originators (like the ones UWM works with, which want to find new borrowers), but it will be interesting to watch.
(Editor’s Note — Mesa or some other company that aspires to compete with Bilt in the mortgage market should send Dan Gilbert an email with the subject line, “Mat Ishbia would hate it if you invested in us.”)
Bilt is also preparing to launch three new versions of its card, which it has spent the last year telling us isn’t a big or important part of its business. And while the company is trying to frame this new product launch as the result of it listening to customer feedback, the real reason is the same reason that it’s been downplaying the card’s importance: the issuing bank behind it isn’t happy.
The Wall Street Journal reports:
Wells Fargo is ending a flashy credit-card partnership that lets people earn rewards points for charging their rent.
The partnership with Bilt had been scheduled to end in 2029, but Wells decided to exit early after it became a money-losing venture, according to people familiar with the matter. Wells warned Bilt it could change the card’s terms otherwise, including tacking on an annual fee of around $250 to $300 for cardholders.
The WSJ article also mentioned that Wells had given the Bilt program a weak internal audit rating within its consumer lending unit due to concerns about money-laundering risks and that the head of consumer lending at the bank had said on an internal call last year that Bilt had become a reputational risk.
That risk, combined with the poor economics of the program for Wells, pushed the bank to essentially threaten Bilt (which it, as a reminder, is an investor in) to find a new partner or else. Here’s the WSJ again:
Wells has tightened underwriting standards in the past year, making it harder for new applicants to be approved, according to people familiar with the matter. The bank indicated it would further tighten standards if the card doesn’t change issuers, one of them said.
In recent weeks, Wells laid out to Bilt the potential consequences if it failed to have a new issuer by June of next year, including the annual fee for cardholders that Wells would pocket. Another possible scenario Wells laid out to Bilt: the bank will stop accepting new applications and eventually move existing Bilt card balances to general-purpose Wells cards.
Bilt announced that it is now working with Cardless, an embedded credit card platform, which currently partners with First Electronic Bank to issue cards for partners, including, most recently, Coinbase.
The transition from Wells to Cardless, which is scheduled to take place early next year, won’t be without its challenges. As Jason Mikula noted over at Fintech Business Weekly, First Electronic Bank is a very small bank ($489 million in assets) and will not be able to absorb Bilt’s existing portfolio ($1.4 billion in outstandings) without Cardless lining up a significantly larger debt facility than the one that it most recently arranged ($75 million in 2023) or bringing in a new, much larger bank partner.
As Wells can attest, riding Pegasus isn’t always as much fun as it appears.
#3: Tax-Advantaged Investment Accounts for Babies! Copy anchor linkCopied
What happened?Copy anchor linkCopied
America is finally going to be launching government-funded investment accounts for babies:
America's babies are becoming investors, each to receive $1,000 seed accounts via the reconciliation bill signed last week by President Trump.
The bill creates a new class of investment account in the tax code.
Every American born between 2025 and 2028 automatically receives an account with $1,000 from the U.S. Treasury, which will be invested in a low-cost index fund.
It would be the property of the child, held in a custodial trust, and money cannot be touched until the child turns 18. At that point it automatically becomes a traditional IRA, although money can be pulled out for uses like education, starting a business, or buying a first home.
Americans under 18 but born before 2025 also are eligible for the accounts, although not the $1,000. Every account can take up to $5,000 in additional contributions per year, including up to $2,500 on a tax-free basis by a parent's employer.
So what?Copy anchor linkCopied
I haven’t been happy with a lot of what Congress and the administration have been doing recently, but this is magnificent.
The roots of this idea stretch back to 2008, when Hillary Clinton (briefly) talked about “baby bonds” as a part of her platform in the U.S. Presidential election. Since then, it has remained a popular idea on the left, where (among other things) it is seen as a cost-effective intervention to address the racial wealth gap in the U.S.
The version that was just signed into law is a bit different. It focuses on index funds rather than treasury bonds, and it sounds like it will be done in partnership with the private market rather than solely by the U.S. government:
[Matt] Lira [a veteran Republican operative who has been leading the lobbying effort on this initiative] says that he appreciates healthy skepticism of gov-built tech, but has confidence that the private sector will be able to provide easy-to-use apps and that Treasury will be able to build the API gateway (much as it did for TurboTax and the like).
He notes that Robinhood built a viable test app for these accounts in just 36 hours.
I’m personally not thrilled about the notion of Robinhood helping to administer these accounts (Congratulations on turning 18! Let us tell you about memestocks and prediction markets!), but everything else about this is excellent and a reason for optimism about the future!
2 READING RECOMMENDATIONS
#1: A Long and Winding Path: A Brief History of Section 1033 of Dodd-Frank (by Tom Brown) 📚Copy anchor linkCopied
Given the big news this week, I figured I’d focus this week’s reading recommendations on different perspectives on open banking, 1033, and the future of consumer-permissioned data sharing in financial services.
This first one from Tom provides a good timeline on Section 1033 and the resulting regulatory and legal maneuvers around it.
#2: What good is an oligopoly if you don’t use it? (by Todd Baker) 📚Copy anchor linkCopied
This second one from Todd gives some good context on the various arguments surrounding open banking and what this move from JPMC means for the industry.
1 QUESTION FROM THE FINTECH TAKES NETWORK
There are a TON of interesting questions being asked in the Fintech Takes Network. I’ll share one question, sourced from the Network, each week. However, if you’d like to join the conversation, please apply to join the Fintech Takes Network.
What are the most interesting recent developments in the mortgage servicing space?
I’ve long been obsessed with mortgage servicing, but it’s been a while since I’ve written about it. What should I dig into? Who should I speak with?
If you have any thoughts on this question, reply to this email or DM me in the Fintech Takes Network!
INPUT REQUESTED!
I’m working with Dilly Labs and the wise and powerful Tom Johnson on a little research project and I am looking for folks who work at a consumer lending company (bank, credit union, non-bank lenders, etc.) and who have experience buying/implementing/working with credit decision engines to fill out a quick survey.
Credit Decision Engine Vendor Survey
I promise it won’t take long! And it will be extremely helpful! So …
_7.png)
(Editor’s Note — If you work at a technology company that sells a credit decision engine, feel free to pass the link to the survey on to your clients. That’s perfectly fine. However, if you attempt to fill out the survey yourself, a terrible curse will befall you and your company. This isn’t a joke. The curse is real.)
Thanks for the read! Let me know what you thought by replying back to this email.
— Alex
