Well, it’s Groundhog Day … again.
Happy Monday, Fintech Takers!
Well, it’s Groundhog Day … again.
And that must mean we’re up here in Montana, waiting to find out how much more fintech winter we can expect.
- Alex
P.S. — Today’s newsletter is an homage to Groundhog Day, one of the greatest films ever made.
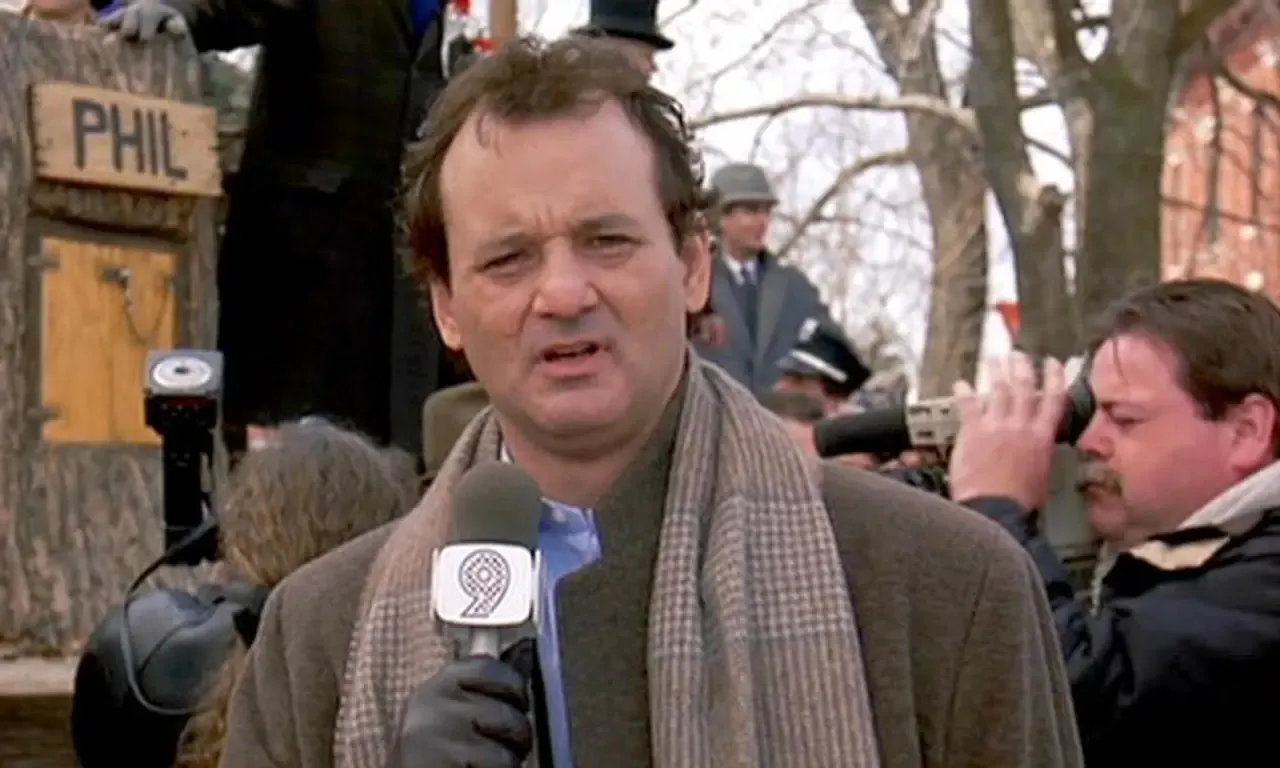
Me, reading the news these days.
3 FINTECH NEWS STORIES
#1: “Maybe he’s not omnipotent, he's just been around so long he knows everything.” Copy anchor linkCopied
What happened?Copy anchor linkCopied
Block is feeling really good about its progress in building up its lending business:
Block today announced it has provided access to more than $200 billion to customers in global lending across its portfolio of credit products, including Cash App Borrow, Afterpay, and Square Loans. Through this work, Block is proving that with the right technology, inclusive lending and responsible risk management aren't opposing forces; rather, they're the foundation of sustainable credit for the next generation. This work across Block’s ecosystem is only possible due to the strength of the company’s novel underwriting technology and customer-first product designs. In fact, since 2013 the company has maintained stable loss rates across all lending products despite exponential growth and changing macroenvironments.
So what?Copy anchor linkCopied
The whole press release is interesting and worth reading, but there are a couple of parts I want to zoom in on.
First, Block believes that the strength of its lending business rests on its unique data:
Block's credit infrastructure uses near real-time behavioral data instead of delayed credit bureau reports. For example, Cash App analyzes earning, saving, spending, and repayment patterns across its 58 million monthly actives to generate an internal Cash App Score for each customer. This approach has enabled 38% more Cash App Borrow loan approvals at the same loss rates compared to traditional credit underwriting, demonstrating that our product design coupled with strong underwriting models can drive materially stronger performance. This is all while maintaining industry-leading performance metrics across all lending products.
The company's integrated ecosystem creates unique advantages that pure-play credit companies and traditional banks cannot replicate. When customers use Cash App for their paycheck, spending, savings, and investments, Block develops a comprehensive financial picture that enables better underwriting and customer experience than fragmented legacy systems.
I think this is true. Every large consumer lender builds its own proprietary underwriting model, rather than relying on the FICO Score, because a specialized model (focused on a specific customer segment) will always outperform a general-purpose model. However, the in-house models that most large banks build are still based, primarily, on credit bureau data because A.) most large banks target prime and super-prime borrowers with full credit files, and B.) most large banks are terrible at leveraging their own internal data, especially across different product silos. Block, by contrast, focuses on younger consumers with thin or missing credit files and has built a unified data ecosystem, which allows for all customer data (spending, savings, investments, P2P transfers, etc.) to filter in as signals in its Cash App Score. This approach works so well (for the short-term unsecured lending products that Block offers) that Cash App doesn’t need to rely on credit bureau data to make risk decisions, even when it is available.
Interestingly, Cash App’s lack of reliance on traditional credit data and scores has motivated the company to start making its Cash App Score visible to its customers:
As Block continues to expand access to credit, the company recently completed a pilot providing select customers visibility into their Cash App Score, a near real-time measure of financial health used for Cash App Borrow eligibility. Via the pilot, customers were able to see what drives their score and take actions to improve it, gaining unprecedented transparency and the ability to unlock more credit through positive financial behaviors.
I think this is a smart move by Cash App. The FICO Score is becoming increasingly unhelpful as a credit education and planning tool for consumers (read this essay to learn why), and that creates an opportunity for other, narrower solutions to fill in the gaps.
However, Block has ambitions to go much further:
Internal testing shows Cash App’s underwriting models deliver significantly stronger predictive accuracy than traditional credit scoring across revolving credit and longer-term loans like auto loans, student loans, and mortgages. Based on a recent analysis, Cash App's models can approve 30% more auto loans at identical loss rates compared to conventional methods.
These results give Block confidence in expanding access within its lending suite and exploring opportunities for the Cash App Score to help customers qualify for external products—auto loans, credit cards, rental applications—through strategic partnerships.
OK, OK. This is where we need to pump the brakes. As Rita tells Phil, “You're not a god — you can take my word for it.”
As good as Block’s internal data and Cash App Score may be, the real strength of its consumer lending business today is product structure and ecosystem control. Cash App Borrow and Afterpay Pay-in-4 are small-dollar and short-duration products (weeks, not years). That matters. Short terms dramatically reduce exposure to macro shifts, and the Cash App ecosystem provides unusually high-frequency signals about income, liquidity, and spending that most lenders simply don’t have.
Block’s strategy — loaning into small pockets of liquidity with near real-time visibility — is very clever, but it does not automatically imply that the Cash App Score will be a useful tool for lenders taking long-horizon, high-balance risks.
Let’s use Block’s claim — that its models could approve 30% more auto loans at the same loss rates — as our example.
You can do all of the backtesting against credit bureau data that you want, but reject inference is far from an exact science. You don’t know how those additional 30% of consumers who would have been approved using your model would have performed because they weren’t actually approved! Lending outcomes are causal. When you give someone another loan, you are altering their financial situation and reshaping their repayment preferences in ways that are very difficult to predict. This is especially true over long time horizons, during which macroeconomic conditions may change dramatically.
Block doesn’t have any experience in auto lending (which is, predominantly, an indirect business controlled by the dealers). It doesn’t have any experience in collateralized lending (where repayment behaviors and collections tactics are very different from those in unsecured lending). It doesn’t have any experience lending money over long time horizons (84-month terms are now very common in auto lending). And it doesn’t have any experience lending through a long, credit-cycle recession like 2008–09 (Block got started lending, on the small business side, in 2014).
In lending, it’s the things you don’t know that kill you. Traditional credit bureau data and general-purpose credit scores are valuable because they give lenders access to knowledge that they don’t know they don’t know.
It’s fine for Block to reject that knowledge and to construct a closed ecosystem where it can lend safely without it. However, it’s a big leap to assume that approach will work well outside that ecosystem.
#2: “Well, what if there is no tomorrow? There wasn't one today!”Copy anchor linkCopied
What happened?Copy anchor linkCopied
LendingClub beat its earnings projections for Q4, and … its stock price went down:
LendingClub reported fourth-quarter results on Wednesday that surpassed analyst expectations and forecasted continued profit growth in 2026, aided by a shift in accounting methodology and expansion into the home improvement lending market.
However, the accounting noise led to a 14% drop in the company's stock price — a dip that analysts chalked up to misplaced expectations related to the book changes.
So what?Copy anchor linkCopied
This is a weird story, and it gets weirder when you understand the “accounting noise” that caused LendingClub’s stock to drop.
Forgive me in advance. I lack Kiah Haslett’s obsessive love of bank accounting, so my explanation here might be a bit simplistic, but I’ll do my best.
Loans are tricky to value because you can’t be certain if they will be paid back. There are two main ways to account for this uncertainty:
- Reserve accounting. When a bank makes a loan, it immediately sets aside some money — usually around 1–2% of the loan — to cover losses it expects over the life of that loan. The downside is that growth looks worse on paper. If you make a lot of new loans in a given year, profits go down in the short term because you’re booking those reserves immediately. The upside is that this approach is conservative, predictable, and easily comparable because it’s the standard for how banks account for their loans.
- Fair-value accounting. Instead of assuming losses upfront, the company estimates what a loan is worth today based on expected cash flows and market pricing. Depending on the circumstances, that estimate can be higher than the loan’s face value, giving the lender a premium on newly-originated assets. The upside is that growth looks better on paper: earnings and return on equity can rise quickly as new loans are added. The downside is that results become more sensitive to assumptions and market conditions, making profits more volatile and harder to compare across lenders, especially when credit conditions worsen.
Historically, LendingClub has used reserve accounting. However, it announced late last year that it would be switching to fair-value accounting, starting on January 1, 2026. That change doesn’t affect how much cash the company actually earns on its loans, but it does affect how and when profits show up in reported earnings. In the short term, it also makes results harder to compare to prior quarters (and to analyst models built under the old rules), which helps explain why LendingClub’s stock price went down even though its earnings in Q4 beat expectations. Analysts were expecting a bigger accounting bump than they got.
But why is LendingClub making this change?
The stated reason is that it matches how LendingClub already runs its business.
LendingClub isn’t a pure-play bank. It’s a hybrid lender. The company originates consumer loans through its bank, then splits them in two directions. Some are sold to investors through its marketplace, generating fee income. Others are kept on LendingClub’s balance sheet, where the company earns interest over time.
Historically, those two sides of the business have been accounted for differently. Marketplace loans are naturally tied to market pricing. LendingClub is literally selling them, so their value is constantly being tested by what investors are willing to pay. Held loans, by contrast, have been treated like traditional bank assets under reserve accounting, with losses booked upfront and earnings spread out over time.
LendingClub’s argument is that this mismatch creates unnecessary friction in the financials. Moving held loans to fair-value accounting makes results more consistent across the business.
The more cynical (though, perhaps, more realistic) reason is that it’s a faster and more lucrative way to grow reported earnings.
Reserve accounting forces banks to take their medicine upfront. Fair-value accounting can do the opposite, allowing lenders to recognize a premium on newly originated loans and report higher profitability earlier in the life of those assets.
If you’re LendingClub, watching SoFi (which has been shamelessly using fair-value accounting for years … like a French noble eating an ortolan in the open air) trade at a higher multiple while, in your view, running a more expensive and operationally messier business, that can start to feel frustrating.
Perhaps LendingClub decided it was tired of being penalized for growth. Adopting fair-value accounting gives it some of the same near-term boost SoFi enjoys, which can lift reported ROE and earnings and create more room to invest aggressively in things like marketing and new products (it’s making a push into home improvement lending) without the numbers looking as painful in the short run.
I personally don’t love LendingClub’s decision, but as Charlie Munger wisely observed, “Show me the incentive, and I'll show you the outcome.”
#3: “I'm betting he's going to swerve first.”Copy anchor linkCopied
What happened?Copy anchor linkCopied
The Wall Street Journal just published an important article:
Four days before Donald Trump’s inauguration last year, lieutenants to an Abu Dhabi royal secretly signed a deal with the Trump family to purchase a 49% stake in their fledgling cryptocurrency venture for half a billion dollars, according to company documents and people familiar with the matter. The buyers would pay half up front, steering $187 million to Trump family entities.
The deal with World Liberty Financial, which hasn’t previously been reported, was signed by Eric Trump, the president’s son. At least $31 million was also slated to flow to entities affiliated with the family of Steve Witkoff, a World Liberty co-founder who weeks earlier had been named U.S. envoy to the Middle East, the documents said.
The investment was backed by Sheikh Tahnoon bin Zayed Al Nahyan, an Abu Dhabi royal who has been pushing the U.S. for access to tightly guarded artificial intelligence chips, according to people familiar with the matter.
The deal marked something unprecedented in American politics: a foreign government official taking a major ownership stake in an incoming U.S. president’s company.
So what?Copy anchor linkCopied
Remember, back in May of last year, when World Liberty Financial's stablecoin, USD1, was used to complete a United Arab Emirates investment firm’s $2 billion investment in crypto exchange Binance? And observers were concerned that the transaction might indicate that some unethical dealings were happening behind the scenes? Concerns that were supercharged when President Trump pardoned Binance founder Changpeng Zhao six months later.
Well, one thing we didn’t know at the time was that the company that owns that UAE investment firm also owns 49% of World Liberty Financial. In fact, two executives from that company sit on World Liberty Financial’s five-person board.
This is bad, on many, many levels, most of which are above my pay grade.
However, it’s a relevant story for those of us working in financial services because World Liberty Financial is trying to compete with banks.
The company announced last year that it would be introducing a debit card in order to bring its stablecoin into more everyday payments. More recently, the company announced that it had applied for a national trust bank charter from the OCC. And despite the obvious conflicts of interest, the OCC stated that it would be moving swiftly to review the application “in an apolitical, nonpartisan and objective manner.”
However, the OCC’s commitment was made before this latest report from the Wall Street Journal, which revealed that a UAE-linked firm quietly acquired a 49% stake in World Liberty Financial (before it had launched any products!) and placed two of its executives on the company’s board — facts that were not previously disclosed.
I’ll be honest. At this point, I don’t see how the OCC can approve this charter and keep its credibility.
The Wall Street Journal’s reporting raises serious questions about who effectively controls World Liberty Financial, how transparent its governance really is, and whether a company with deep foreign-state ties should be granted the privileges of a U.S. national bank charter.
For the OCC, which is charged with safeguarding the integrity of the U.S. banking system, the issue is no longer merely whether World Liberty can meet the technical, operational, and legal requirements of being a national trust bank. It is whether granting a federal banking charter to this particular company, at this particular moment, would undermine public confidence in the neutrality of bank supervision and entangle the agency in conflicts it is ill-equipped to manage.
It seems clear to me that it would, but we will see what the OCC thinks.
SPONSORED BY MX


As we head into the NFL playoffs, here's a stat that should give you pause: The most financially vulnerable consumers spend nearly twice as much on gambling.
This is MX’s monthly Data Takes. Every month this year, I'll share an interesting data point from MX to help you better understand and support consumers.
I've said it more than once and I'll say it again: gambling is THE #1 threat to consumers' financial health. New data from MX shows the real scale of the fallout—and how fast it’s accelerating.
2 READING RECOMMENDATIONS
#1: ‘Fundamental reset’: Scott Bessent has a plan to free the nation’s banks (Politico) 📚Copy anchor linkCopied
I remember talking to someone last year about what Scott Bessent and Jonathan McKernan were doing at Treasury, and how it seemed very different from how prior leadership at Treasury had engaged with bank regulatory agencies.
The person I was speaking with dismissed my theory, but this report from Politico would suggest that I was correct in my original observation: Bessent and McKernan are taking an unusually aggressive and proactive role in reshaping bank regulation.
#2: The Economic Case for Credit Card Interest Rate Caps (by Elena Botella, Open Banker) 📚Copy anchor linkCopied
It’s very important to read arguments that cut against the conventional wisdom (especially if you agree with the conventional wisdom), and this article certainly does that.
Elena makes a fairly compelling case for a credit card interest rate cap, though she also acknowledges that 10% is likely too low (on this point, consumer advocates seem to broadly agree).
From my perspective, this whole discussion comes down to access versus misuse. A cap on interest rates would reduce access to credit cards. That’s the whole point. The question is whether that reduction in access would be a net good (less harmful revolving debt) or a net bad (less access to needed liquidity) for consumers.
FIVE FUN FACTS ABOUT GROUNDHOG DAY
In place of our typical question of the week, allow me to share with you some of my favorite facts about the movie Groundhog Day:
- The film was written by Danny Rubin. The earliest versions of his idea focused on how a person would behave if they were immortal, but Rubin modified the premise from traditional immortality to being trapped in a time loop because he knew it would be too expensive to make a movie showing someone living through multiple eras of history. He picked Groundhog Day because he wanted the movie to be on a recognized holiday, but one that didn’t get widespread attention.
- The cause of the time loop isn’t revealed in the movie, which was an intentional choice by Rubin and director Harold Ramis. They wanted the audience to focus on the philosophical dilemma rather than the temporal mechanics. However, the studio insisted that they explain why the time loop was happening, so Ramis and Rubin wrote a scene to explain it, but intentionally scheduled the scene to be shot too late in the production schedule so that it wouldn’t be included.
- It’s also never made clear how long Phil spends trapped in the time loop, though many people have attempted to calculate it over the years. Ramis himself guessed 30-40 years, based on how long it takes to master skills like ice sculpting and speaking French (and allotting for some downtime and misguided exploits).
- Bill Murray didn’t want to shoot the pivotal scene with Phil breaking out of the time loop and finding Rita next to him until he knew what Phil was wearing. Would he be in the same clothes from the previous night, or different clothes (indicating something had happened between Rita and Phil)? So Ramis polled the cast and crew. Half said he should be wearing the same clothes, and the other half said different clothes. The tie was broken by a young female crew member who said, “Bill is wearing exactly what he wore the night before. If you do anything else, it will ruin the movie.”
- Murray and Ramis, who had a long friendship and history of successful collaborations up to that point, had a terrible falling-out during the making of the film (Murray was going through a divorce at the time and was, reportedly, very difficult on set). This led to an estrangement that lasted more than 20 years. However, they reconciled shortly before Ramis died in 2014, which, in keeping with the film’s central theme, proves that it’s never too late to fix a mistake.
Thanks for the read! Let me know what you thought by replying back to this email.
— Alex
Join 2,444 other finance and fintech leaders in the Fintech Takes Network
The conversation doesn't have to stop here
Keep learning and connecting in the Fintech Takes Network
EVENTS | FEED | LIBRARY | DIRECTORY
