What Is Tempo? And Why Do We Need It?
Highlights from the Fintech Takes Podcast
Happy Wednesday, Fintech Listeners!
There’s no snow on the ground right now in Bozeman, but don’t take that to mean that it’s warm! Or that the snow won’t return soon! I think it’s very likely that my kids will be wearing coats over their Halloween costumes on Saturday, which is a long-standing tradition here in Montana.
I’ve got a wonderful podcast for you today, so grab your headphones and let’s dive in!
— Alex
3 BIG IDEAS FROM THE PODCAST
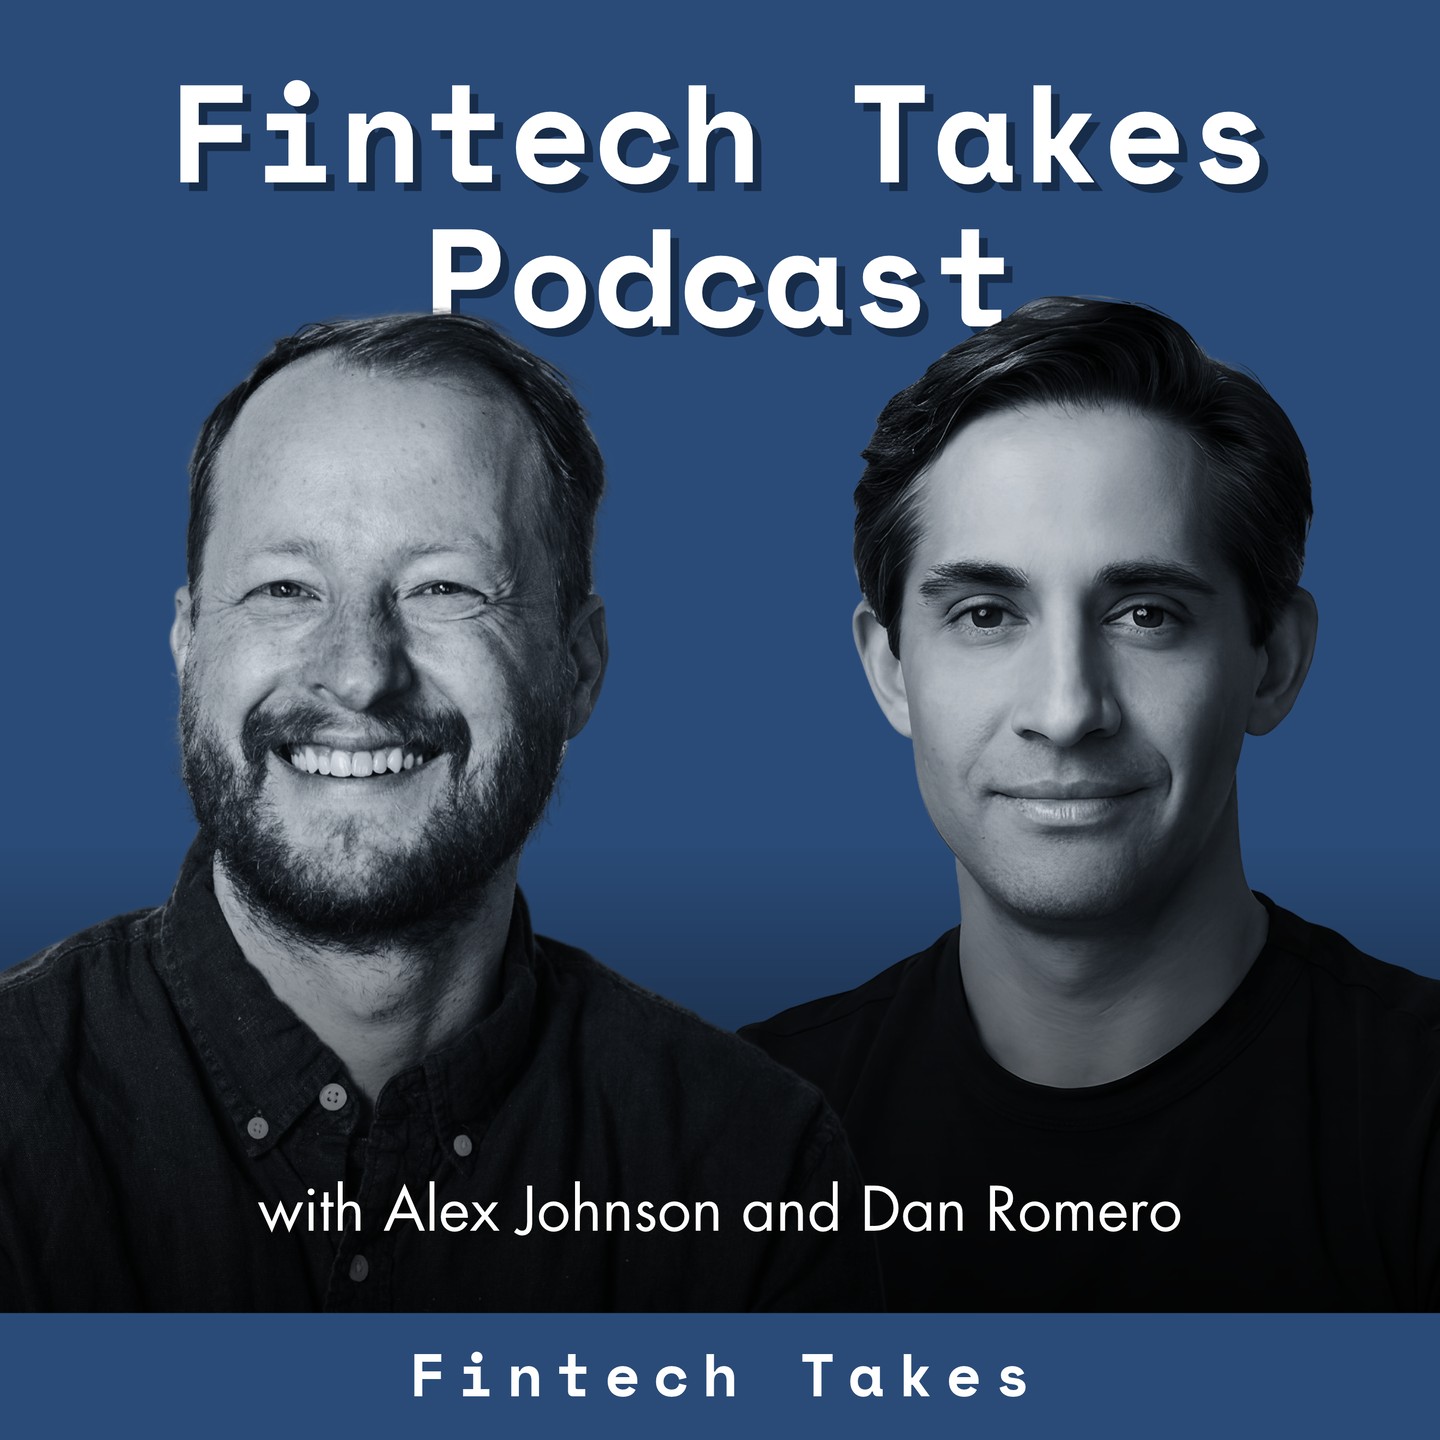
I have a treat for all of you (and no tricks, I promise!)
In today's episode, I sit down with Dan Romero, who leads GTM at Tempo, the payments-focused blockchain co-created by Stripe and Paradigm. And together, we dive deep into crypto’s future as payments infrastructure.
Dan’s fluent in both crypto and payments, which made him the right person to explain Tempo to me as if I were a community bank CFO living under a rock.
From there, we got into the design decisions Tempo and Stripe are making today that won’t get graded for 5, 10, 15, hell even 20 years. Payment nerds, rejoice!
Tune in for the full conversation here
And read below for my three big ideas...
#1: What If Visa Had to Compete with the NYSE?Copy anchor linkCopied
Dan offered an interesting analogy for understanding why Stripe and Paradigm decided to build Tempo, a blockchain specifically designed for payments.
Imagine taking the New York Stock Exchange and Visa and putting them on the same infrastructure.
That's essentially how general purpose blockchains work today. Payments compete for block space (the network's finite transaction processing capacity) with crypto trading. And when the network gets congested, the price of that capacity goes up. Think Uber surge pricing, except the person desperate to trade a memecoin can outbid the person who just wants to send a payment.
“If that existed in TradFi,” Dan said, “Visa would be outcompeted for that kind of bandwidth because stock trades are more valuable.” Which is why, in his words, “no one does that because you have separate concerns.”
For a trader, paying more to execute a potentially profitable trade might be perfectly rational. For a business processing millions of payments, a transaction fee that jumps from a tenth of a cent to a dollar is a nonstarter.
This gets at a fundamental distinction between financial markets and payment networks. Payments need predictable costs and reliable access, particularly at enterprise scale.
Tempo's answer is a dedicated payments lane that prioritizes transactions even when the broader network is congested. The tradeoff is intentional; Tempo may be less attractive for crypto trading, but that's fine with them. It wasn't built for traders; it’s not congruent with their business model.
That specialization also helps explain why Tempo is a layer one (L1) blockchain rather than a layer two (L2) network built on top of something like Ethereum. L2s depend on an underlying blockchain for security and settlement. Tempo's bet is that payments warrant their own infrastructure, without dependencies on another chain.1
What's interesting is how this challenges a longstanding assumption in crypto; that the blockchain can accommodate virtually any kind of financial activity. Dan believes plenty of capital markets activity will eventually migrate onchain. But that doesn't mean stock trading and payments should compete for the same network capacity.
Sometimes the most important infrastructure innovation is deciding what not to optimize for.
#2: Consumer Protections Vs. StablecoinsCopy anchor linkCopied
One of my favorite moments in this conversation was the question around what happens to consumer protections when payments become instant and final.
Card networks have chargeback rules. Banks have recall and return mechanisms. Blockchain settlement, by contrast, is generally irreversible. Once the payment settles, you can't simply call Visa and dispute the underlying transfer.
For certain transactions, that's a feature.2 But other transactions need those protections, too. Does that mean stablecoins have to reproduce the entire infrastructure for disputes, refunds, and recourse?
Not necessarily, according to Dan.
He pointed out that stablecoins, at least today, are principally a B2B infrastructure technology. Even when they touch consumers, the underlying complexity can be abstracted away.
Consider a global marketplace that pays contractors in digital dollars. A recipient might hold those funds in a wallet, earn a yield, or spend through a debit card. The underlying balance sits on a blockchain, but the card transaction still travels over Visa's network, with its existing protections.
The recipient might never know which stablecoin they're using.That's what Dan means when he describes stablecoins as a modular building block. Businesses can assemble financial products with different components, choosing established networks for functions those networks already perform well.
Of course, modularity raises its own questions. What happens when a contractor earns yield through a DeFi protocol and that protocol gets hacked?
Dan thinks insurance products will emerge to cover those risks, perhaps reducing a 4.5% yield to 4.2% in exchange for coverage (again, this is Dan’s prediction, not a current reality). But regardless, there’s a larger opportunity here to make financial products more configurable without assuming every component must provide every function.
That is, as long as the corresponding responsibility is also clear: Someone still has to determine which protections apply, who provides them, and who bears the loss when something goes wrong.
#3: Can Stripe Build Infrastructure Its Competitors Trust?Copy anchor linkCopied
I asked Dan a question that I suspect anyone competing with Stripe has considered.
Stripe owns Bridge and Privy, helped create Tempo, and is one of the organizing forces behind Open Standard. Look at those pieces together and you can see the outline of a vertically integrated stablecoin payments business.
Now imagine you're Adyen or PayPal. Would you really want to build your business on infrastructure controlled by one of your competitors?
Dan called that a completely valid skepticism. His answer was that neutrality can’t simply be a promise. It has to be demonstrated through behavior over time.
Bridge customers can issue stablecoins on chains other than Tempo. Privy wallets can hold different stablecoins. Tempo supports multiple stablecoins, including USDT, and its permissionless architecture means developers don't need Stripe's approval to build on it.
That last point led to an interesting comparison with core banking.
Traditional core providers can impose technical and contractual constraints that make it extraordinarily difficult for a bank to leave. Public blockchains offer a different kind of portability. A company dissatisfied with Tempo could potentially move its application to another compatible chain while retaining its chosen stablecoin. Or it could switch stablecoins without leaving Tempo.
That's not to say migration would be effortless, but the technical architecture changes the relationship between infrastructure providers and their customers.
I offered American Express as a useful TradFi analogy; a company can operate a payment network, issue its own cards, and simultaneously support third-party issuers that compete with it. The difference is that blockchain's permissionless design provides some technical assurance of access and portability, beyond a contractual promise.
Dan acknowledged that Tempo still has to establish its neutrality over years of consistent treatment, which gets at an interesting tension. Stripe is assembling more pieces of the payments infrastructure stack, but the blockchain architecture is designed to make those pieces easier for customers to swap out.
I’ve always liked companies that impose constraints on themselves, and handing your competitors an exit ramp they can waltz through whenever they please is about as constraining (and as confident) as infrastructure strategy gets.
WHAT I'M LISTENING TO
#1: Why Ramp is Worth $60bn (Brainfood) 🎧Copy anchor linkCopied
I’ve been wondering about this exact question!
Apparently, Ramp is a productivity company, not a fintech company.
Interesting conversation between Simon and Eric.
#2: Nu Way of Banking: Nubank Makes Its Mark in the U.S. and More (Breaking Banks) 🎧Copy anchor linkCopied
I truly cannot wait to see how Nubank does in the U.S. I am fascinated by the challenge they have taken on.
*Bonus: Collections Conversations (by me, with C&R Software) 🎧Copy anchor linkCopied
Tal Schwartz of North Exit Ventures puts Canada five to eight years behind the U.S. on fintech product innovation, and argues the lag helps because founders watch what works while regulators watch what fails. Episode 3 of Collections Conversations applies that lens to servicing, including why the mortgage renewal wave may surface in card and auto-loan delinquencies before it reaches mortgages. It's worth a listen if your work touches collections.
*This rec is brought to you by one of our fantastic brand partners.
Thanks for the read! Let me know what you thought by replying back to this email.
— Alex